Buying property in Victoria involves more than inspecting a home and negotiating the price. Before signing a contract of sale, buyers should understand the property’s legal details, financial obligations and any restrictions that could affect how they use it.
One of the most important documents to review is the Section 32 vendor statement, also known as the vendor’s statement. The seller must provide this document before the buyer signs the contract, and it discloses key information about the property under Victorian law.
However, receiving a Section 32 statement does not mean every aspect of the property has been checked. Buyers still need to investigate the building’s condition, planning restrictions, potential costs and other risks before committing to a purchase.
What Is a Section 32 Vendor Statement?
A Section 32 vendor statement is a legal disclosure document required under section 32 of Victoria’s Sale of Land Act 1962. The seller, legally known as the vendor, must sign the statement and provide it to the buyer before the buyer signs the contract of sale.
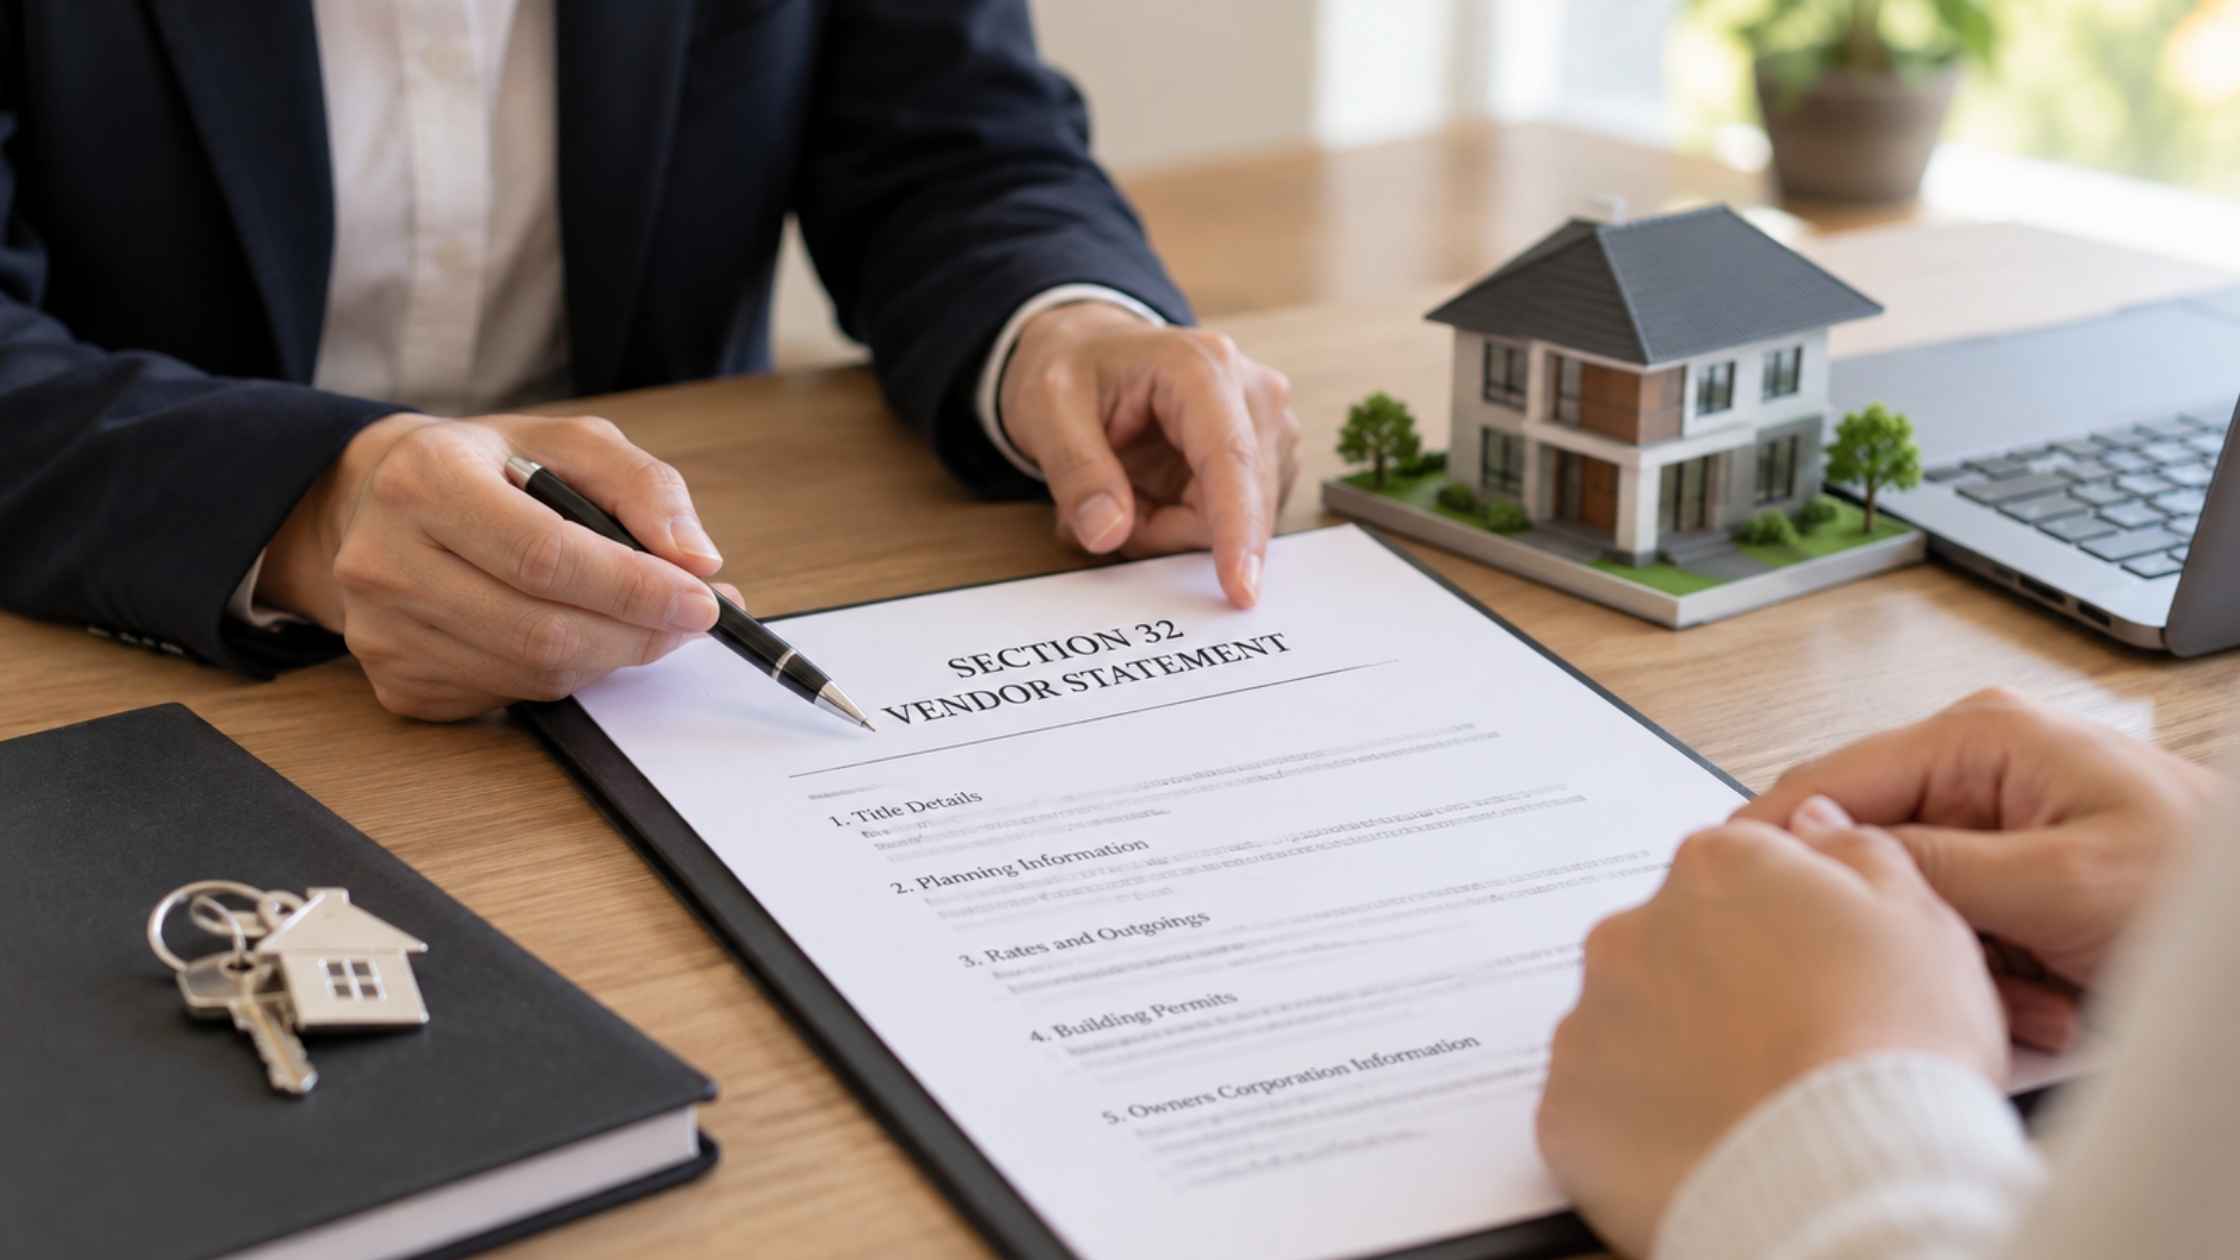
The document provides information about matters that may affect the property or the buyer’s ownership. Depending on the property, it can include title details, mortgages, easements, covenants, planning information, rates and taxes, building permit information and owners corporation documents.
The seller usually engages a solicitor or licensed conveyancer to prepare the statement. The selling agent typically makes it available to prospective buyers along with the contract of sale.
Buyers should not treat the document as a formality. Its contents can reveal restrictions, ongoing expenses or legal issues that may affect the property’s suitability as a home or investment.
What Information Does a Section 32 Statement Contain?
The required information depends on the property and the disclosures required by law. Buyers should pay particular attention to the following areas.
- Title details, mortgages and ownership restrictions
The statement includes information about the property’s title and certain financial interests or restrictions affecting the land. This may include mortgages, easements and covenants.
A mortgage registered against a property is not necessarily a reason to avoid buying it. The important question is whether the seller will properly discharge the mortgage at settlement or whether any relevant interest will remain.
Easements can give another party certain rights over part of the land. For example, an easement may allow access for drainage, sewerage or other services. Covenants can restrict what an owner may do with the property, including certain building or land-use activities.
Buyers should ask their conveyancer to explain any restrictions that could affect renovations, extensions, development plans or future resale.
- Rates, taxes and other property outgoings
The statement also provides information about applicable rates, taxes and other outgoings. These details help buyers understand some of the financial obligations associated with ownership.
Investors should consider these expenses alongside mortgage repayments, insurance, maintenance and expected rental income. A property with higher ongoing costs may produce a lower net return than the advertised rent suggests.
Review the disclosed amounts and ask questions if anything appears unclear or inconsistent. Some costs may change after settlement, so buyers should confirm the amounts that will apply to their ownership rather than assuming every figure will remain fixed.
- Planning controls and notices
Planning information can affect what buyers may do with a property. The statement includes prescribed planning details, such as zoning and relevant overlays, along with certain notices or other matters required by law.
Zoning and overlays can affect development potential, permitted uses and the approvals required for proposed work. A property that appears suitable for an extension or redevelopment may face restrictions that are not obvious during an inspection.
Buyers should confirm planning information with the relevant council or planning authority if they intend to renovate, subdivide, develop or change the property’s use. They should also ask their conveyancer to explain any disclosed notices or restrictions that may affect their plans.
- Building permits and owners corporation information
Where required, the statement includes particulars of relevant building permits issued during the prescribed period. This information can help buyers identify past building work that warrants further investigation.
However, the presence of a permit does not prove that all work was completed correctly or that the property has no defects. Buyers should investigate renovations, extensions and other alterations separately.
For apartments, units and other properties within an owners corporation, the statement also includes prescribed owners corporation information. Buyers should review the available records for details about fees, maintenance, planned works and other obligations associated with shared property.
What Should Buyers Check Before Signing?
Receiving the Section 32 statement is only the first step. Buyers should review the information carefully and ask a qualified conveyancer or property lawyer to investigate any concerns before they commit.
- Check that the statement is complete and current
Confirm that the statement identifies the correct property and includes the required information and supporting documents. Ask your conveyancer whether the searches, certificates and other records are sufficiently current for the proposed purchase.
Documents can become outdated, and circumstances may change between preparation and settlement. If something appears incomplete, inconsistent or unclear, request clarification before signing.
Do not assume an estate agent’s explanation replaces independent legal advice. The agent may help locate documents, but your own conveyancer or solicitor can assess the legal implications for your purchase.
- Investigate easements, covenants and title restrictions
Read the title information with your intended use in mind. If you plan to build an extension, add a dwelling, subdivide the land or make substantial improvements, restrictions could affect whether the project is possible.
Ask your conveyancer to explain any easements or covenants and whether they limit access, building locations or other uses. If necessary, seek planning or building advice before proceeding.
These checks are particularly important for investors buying properties for renovation or development. A restriction that seems minor for an owner-occupier could materially affect an investment strategy.
- Review owners corporation records for apartments
If you are buying an apartment or unit, investigate the owners corporation’s financial position and maintenance obligations. Review the available certificate and records for fees, insurance, meeting decisions, planned works and disputes.
Pay particular attention to major repairs, building defects and proposed special levies. These issues may lead to costs beyond the regular owners corporation fees.
A Section 32 statement may include the required owners corporation documents, but buyers should ask their conveyancer whether additional records or updated information are needed. You can also read Citadel Agency’s article on special levies in strata properties to learn more about this investment risk.
- Compare disclosed costs with your investment budget
Use the information in the statement to check the property’s expected holding costs. Consider rates, taxes, owners corporation fees where applicable, insurance, maintenance and any disclosed obligations that could require additional spending.
If the property is an investment, assess these costs against realistic rental income and vacancy assumptions. A purchase price that appears attractive may be less appealing once you account for ongoing expenses or planned works.
Ask questions before signing if the figures do not align with the information supplied by the agent or other property documents.
What a Section 32 Statement Does Not Tell You
A Section 32 statement is important, but it is not a complete assessment of the property. Consumer Affairs Victoria explains that it does not provide a report on the building’s physical condition, confirm compliance with building regulations or guarantee the accuracy of title measurements.
Buyers should arrange additional checks based on the property’s type, age and intended use.
A building inspection can identify visible defects, deterioration and other issues that may require repairs. A pest inspection can help identify evidence of termites or other timber pests. Neither replaces a legal review of the contract and title.
Buyers may also need to investigate planning approvals, flood or bushfire exposure, drainage, boundary matters and the availability of essential services. The appropriate checks depend on the property and the buyer’s plans.
For investment properties, this broader due diligence can help uncover risks that affect rental appeal, maintenance costs, future improvements or resale value.
What Happens If the Section 32 Statement Is Incorrect or Incomplete?
The seller must provide a statement that meets the legal requirements. If the statement is missing, incomplete or contains incorrect information, the buyer may have legal rights under Victorian law.
However, buyers should not assume that every error automatically allows them to cancel the contract. The outcome depends on the nature of the problem, the relevant legal provisions and the circumstances of the transaction.
If you discover a potential issue, contact your conveyancer or solicitor immediately. Avoid relying on informal assurances or attempting to withdraw without advice, as an invalid withdrawal could expose you to contractual consequences.
The safest approach is to have the statement reviewed before signing. This gives you a chance to seek clarification, investigate concerns and make an informed decision while you still have the opportunity to negotiate.
How Does a Section 32 Statement Fit Into Property Due Diligence?
A Section 32 statement should form part of a broader due diligence process rather than serve as the only document a buyer reviews.
Start by having your conveyancer check the statement and contract of sale. Arrange building and pest inspections where appropriate, confirm finance and investigate any planning or title issues that could affect your plans.
If you are buying an apartment, review owners corporation information and consider the condition of shared areas and major building components. If you are buying a house or development site, investigate the property’s boundaries, planning controls and suitability for your intended use.
Investors should then bring these findings together with rental estimates, purchase costs and ongoing expenses. This helps establish whether the property aligns with their strategy and remains financially viable after allowing for potential risks.
Frequently Asked Questions
- When should a buyer receive the Section 32 statement?
The seller must provide the signed statement before the buyer signs the contract of sale, subject to the requirements of Victorian law. Buyers should request it as early as possible so their conveyancer has time to review the document before an offer or auction commitment. - Can I review a Section 32 statement myself?
You can read the statement and note any questions, but a solicitor or licensed conveyancer should review it before you sign. Legal documents may contain technical details about title restrictions, statutory disclosures and obligations that are difficult to interpret without specialist knowledge. - Does a Section 32 statement include a building inspection?
No. The statement is a legal disclosure document, not a building condition report. Buyers should arrange a separate inspection by a suitably qualified professional to assess the property’s physical condition. - Is a Section 32 statement required when buying at auction?
The seller generally must provide the required Section 32 statement before the buyer signs the contract, including in auction transactions. Buyers should review both the statement and contract before bidding because auction purchases generally do not provide the usual statutory cooling-off period. - Can I back out of a property purchase if the Section 32 is wrong?
Potentially, but it depends on the nature of the error, the applicable law and the circumstances. Seek advice from your conveyancer or solicitor immediately before taking action. Do not assume that every mistake automatically gives you the right to withdraw.
Final Thoughts
A Section 32 vendor statement gives buyers important information about a property’s legal, financial and planning circumstances before they sign a contract. Reviewing it carefully can help identify restrictions, costs and issues that deserve further investigation.
However, the statement is only one part of the buying process. Buyers should also arrange appropriate inspections, review the contract, investigate planning matters and assess the property’s ongoing costs.
For investors, these checks are especially important because hidden restrictions or unexpected expenses can affect cash flow, future improvements and resale options. A thorough due diligence process helps you make decisions based on the property’s full circumstances, not just its asking price.
Considering an investment property? Visit Citadel Agency to explore our property investment services. Have questions or ready to get started? Contact our team to discuss your property investment goals.